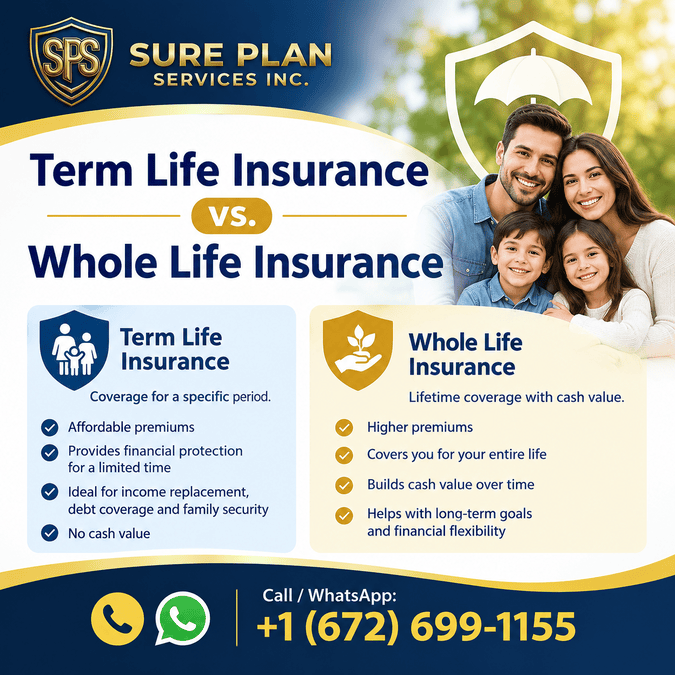
Choosing the right life insurance policy is an important step toward protecting your family’s financial future. In Canada, two popular options are term life insurance and whole life insurance. Both provide financial protection for your loved ones, but they differ in coverage duration, cost, savings features, and long-term benefits.
Understanding the differences between these policies can help you select coverage that matches your financial goals, family responsibilities, and budget. Sure Plan Services can help you explore your options and make a more informed life insurance decision.
What Is Term Life Insurance?
Term life insurance provides coverage for a specific period, such as 10, 20, or 30 years. If the insured person passes away while the policy is active, the beneficiaries generally receive the tax-free death benefit, subject to applicable Canadian tax rules.
Term life insurance is often a practical choice for people who want affordable coverage during important financial stages, such as raising children, paying a mortgage, or supporting a spouse.
Key Benefits of Term Life Insurance
- Affordable premiums: Term insurance generally costs less than whole life insurance for the same initial death benefit.
- Flexible coverage periods: You can choose a term that aligns with your financial responsibilities.
- Family financial protection: The death benefit can help cover mortgage payments, everyday expenses, education costs, and outstanding debts.
- Straightforward coverage: Term policies generally focus on providing protection rather than building cash value.
- Suitable for temporary needs: It can help protect your family during the years when they depend most heavily on your income.
Potential Disadvantages of Term Life Insurance
Term insurance does not generally build cash value. Coverage typically ends when the term expires unless the policy is renewed or converted under its terms. Renewal premiums may increase significantly, and obtaining new coverage later could be more expensive or difficult because of changes in age or health.
What Is Whole Life Insurance?
Whole life insurance is a type of permanent life insurance designed to provide lifelong coverage, provided the policy remains in force and its requirements are met. Unlike term insurance, whole life insurance generally includes a cash value component that grows over time according to the policy’s guarantees and, where applicable, participating policy performance.
Whole life insurance may appeal to people who want permanent protection and a policy that can contribute to their long-term financial planning.
Key Benefits of Whole Life Insurance
- Lifelong coverage: The policy is designed to remain in force for your lifetime when its conditions are satisfied.
- Cash value accumulation: A portion of the premiums supports the policy’s cash value, subject to the contract.
- Predictable premiums: Many whole life policies offer guaranteed premiums that do not increase with age.
- Estate planning support: The death benefit can help provide funds for beneficiaries, estate expenses, or legacy goals.
- Potential policy flexibility: Depending on the contract, you may be able to borrow against cash value, surrender the policy for its available value, or access participating policy dividends if offered.
Potential Disadvantages of Whole Life Insurance
Whole life insurance usually costs considerably more than term insurance for the same initial death benefit. Cash value may take time to accumulate, and surrendering a policy early can result in receiving less than the total premiums paid. Policy loans, withdrawals, and other transactions may reduce the death benefit or have tax implications.
Dividends on participating policies are generally not guaranteed, so it is important to distinguish guaranteed benefits from projected values.
Term Life Insurance vs. Whole Life Insurance: Key Differences
Here is a comparison of the two options for Canadians.
| Feature | Term Life Insurance | Whole Life Insurance |
|---|---|---|
| Coverage duration | A selected term, such as 10, 20, or 30 years | Designed to last for life |
| Premium cost | Generally lower initially | Generally higher |
| Cash value | Usually none | Builds cash value under the policy |
| Premium structure | May increase at renewal | Often level and guaranteed |
| Best suited for | Temporary financial responsibilities | Lifelong protection and legacy planning |
| Savings component | No built-in cash value in standard term policies | Yes, subject to policy terms |
| Estate planning | Can provide protection during a chosen period | Can support long-term legacy goals |
| Policy complexity | Generally simpler | Usually more complex |
Actual premiums and benefits depend on factors such as age, health, smoking status, coverage amount, policy design, and insurer underwriting.
Which Is More Affordable in Canada?
For many Canadians, affordability is a major consideration when comparing life insurance policies.
Term life insurance is generally the less expensive option because it provides protection for a limited period and typically does not include a cash value component. This can make it attractive to young families, homeowners, and people with significant financial obligations.
Whole life insurance generally requires higher premiums because it provides permanent coverage and includes a cash value feature. However, it may be worth considering for individuals who can comfortably afford the premiums and want lifelong insurance protection.
When comparing quotes, look beyond the initial price. Consider how long you need coverage, whether premiums can change, and whether the policy offers the guarantees and features you actually need.
When Should You Choose Term Life Insurance?
Term life insurance may be the better option if you:
- Have young children or dependants who rely on your income.
- Want to protect your mortgage or other significant debts.
- Need substantial life insurance coverage on a limited budget.
- Want protection until your children become financially independent.
- Expect your financial obligations to decrease over time.
For example, a Canadian homeowner with a 20-year mortgage and young children might consider a 20-year term policy to provide financial protection during those important years.
The appropriate coverage amount should reflect outstanding debts, income replacement needs, future education expenses, existing savings, and other available resources.
When Should You Choose Whole Life Insurance?
Whole life insurance may be worth considering if you:
- Want permanent life insurance protection.
- Have long-term estate planning or legacy goals.
- Prefer a policy with guaranteed premiums and specified guaranteed benefits.
- Want to build cash value within an insurance policy.
- Can comfortably maintain higher premiums over the long term.
For example, someone who wants to leave money to their beneficiaries regardless of when they pass away may consider whole life insurance as part of a broader financial plan.
Before purchasing, review the policy’s guaranteed cash value schedule, any non-guaranteed projections, surrender provisions, and available alternatives.
Can You Have Both Term and Whole Life Insurance?
Yes. Some Canadians choose to combine term and whole life insurance to address different financial needs.
For example, a person may purchase whole life insurance for permanent protection and add term insurance to provide additional coverage while raising children or paying a mortgage.
This strategy can balance long-term goals with temporary financial responsibilities. However, owning multiple policies increases the total premium cost, so the arrangement should fit your budget and financial priorities.
How to Choose the Right Life Insurance Policy in Canada
Before selecting a policy, consider these important factors:
1. Identify your financial responsibilities. Calculate how much money your family would need to manage household expenses, debts, childcare, and future education costs.
2. Set a realistic budget. Choose premiums that you can maintain without compromising other essential financial goals.
3. Decide how long you need coverage. If your main concern is protecting your family until a mortgage is paid off, term insurance may be suitable. If you want lifelong protection, whole life insurance may be worth exploring.
4. Compare policy features. Review the death benefit, premium guarantees, renewal terms, conversion options, exclusions, and any cash value provisions.
5. Understand the tax implications. Life insurance death benefits are generally received tax-free by individual beneficiaries in Canada, although exceptions and other tax considerations can apply. Cash value transactions and policy ownership arrangements may have different consequences.
6. Review your policy regularly. Major life events, such as marriage, having children, buying a home, or starting a business, may change your insurance needs.
Final Thoughts: Term Life Insurance vs. Whole Life Insurance
So, which is better for you: term life insurance or whole life insurance in Canada?
The answer depends on your financial situation and long-term goals. Term life insurance may be the better choice if you need affordable protection for a specific period. Whole life insurance may be more appropriate if you want lifelong coverage, cash value accumulation, and support for long-term estate planning.